
|
|
United Kingdom
English
United States
English
Botswana
English
Brazil
Português
Canada
English
Canada
Français
Chile
Español
China
繁體中文
Costa Rica
Español
El Salvador
Español
Guatemala
Español
Honduras
Español
Hong Kong
English
Hong Kong
繁體中文
India
English
Kenya
English
Malawi
English
Mexico
Español
Namibia
English
Nicaragua
Español
Philippines
English
Rwanda
English
South Africa
English
Tanzania
English
Trinidad and Tobago
English
Uganda
English
Zambia
English
Zimbabwe
English
Report
Q2 2026 Credit Industry Insights
Consumer Unsecured Debt-to-Income Ratio at Record Low
Q2 2026 Report highlights include:
- UK households owe more than ever, but unsecured debt burdens relative to income remain at historic lows
- Credit industry growth is increasingly generated by existing borrowers taking additional products, rather than new consumers entering the credit market
- Credit participation remains comparatively low, leaving headroom for responsible market growth
Research by TransUnion shows that UK households owe more than ever on their credit repayment obligations, with outstanding unsecured debt balances continuing to grow at a high rate. However, the significant growth in median income has broadly kept pace with, and at times outpaced, growth in debt per borrower, with debt relative to income sitting at the lowest level since 2019.
Overall, the growth in consumer indebtedness appears to have been manageable. However, signs of pressure are emerging in parts of the credit market, with rising consumer delinquency rates observed across credit cards and unsecured loans. While consumer delinquency rates are the highest since Q2 2021, they are still significantly below pre-pandemic levels.
Q2 2026 Metrics for Consumer Credit Products1
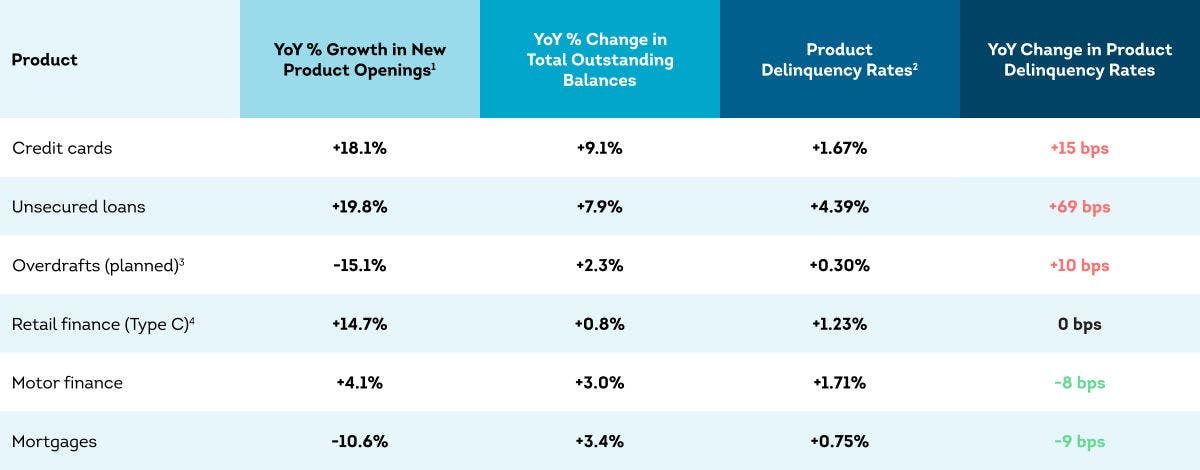
1All statistics shown reflect market positions at end-Q2 2026, except for originations (product openings) statistics which are derived from data covering Q1 2026.
2Account-level serious delinquency rate, measured as a percentage of accounts three or more months in arrears.
3Planned overdraft: Current accounts with a pre-arranged overdraft facility and set credit limit.
4Retail Finance (Type C): Traditional point‑of‑sale finance used for a single purchase and repaid in instalments over time, usually for medium to higher value purchases, excluding BNPL (Type A).
Source: TransUnion UK Consumer Credit Database
“The market is adding credit relationships faster than it is adding new credit participants. Participation remains below pre-pandemic levels, so the opportunity is not simply to offer more products to existing borrowers, but to identify new consumers for whom responsible access to credit could create lifetime value.”
James O’Donnell, Director of Research & Consulting at TransUnion in the UK
About the UK TransUnion CIIR Report
TransUnion’s quarterly UK Credit Industry Insights Report (CIIR) provides a clear, data driven view of consumer credit trends across the UK. Drawing on TransUnion’s robust national credit database, the report tracks key indicators of consumer behaviour and aggregate market movements across mortgages, credit cards, personal loans, motor finance, retail finance and overdrafts. The report focuses primarily on three dimensions across originations (new credit accounts opened), balances (outstanding total and average lending balances) and delinquencies (accounts in payment arrears).
It delivers account level and consumer level insights spanning the most recent nine quarters, enabling the identification of emerging consumer credit trends and tracking of shifts in demand and supply throughout the economic cycle.
DOWNLOAD THE REPORT NOW
The submission has failed.

Information for Good®.
Connect with us
